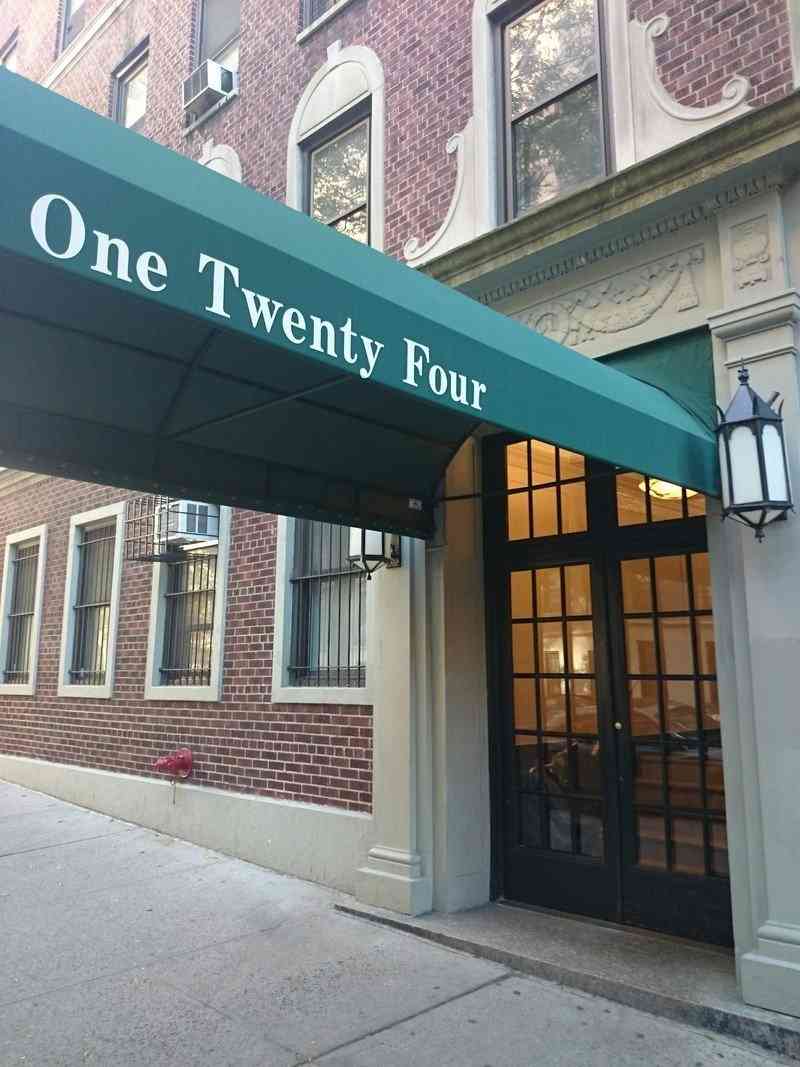
The Westerly (124 West 93rd Street)
124 West 93rd Street, New York, NY 10025
BBL 1012237502 · BIN 1070916
- Year built
- 1924
- Type
- Condominium
- Units
- 53
- Floors
- 9
- Pets
- Not documented in the records located for this page — confirm with the managing agent
- Landmark status
- Not an individual landmark; not in a historic district
- NYC Landmarks Preservation Commission and City Planning records, updated February 2026
- Doorman
- Part-time doorman
Every recorded sale at this building, 2003–2026
Price-per-square-foot over time, the line- and floor-premium curves, and every recorded sale.
- Median $/sf, 2026 to date
- $1,060
- floor-adjusted, 1 sale
- Listing discount
- 0.6%
- Recorded sales
- 67
- On record
- 2003–2026
Own an apartment here? See what it would sell for.
A Private Pricing Opinion — what your apartment at The Westerly would likely sell for today, what it costs to sell, and what you’d walk away with — reviewed personally against condition, exposures, renovation quality, and the competition actually on the market.

The Westerly is a 1920s nine-story apartment house on a quiet Columbus–Amsterdam block that converted to condominium rather than cooperative. On this stretch of the Upper West Side, almost every prewar building of its size is a co-op. The condominium form changes the buyer's position: there is no co-op board interview, and purchases run through the condominium's application and right-of-first-refusal process; confirm financing and LLC or trust ownership rules in the declaration and bylaws. For a one-bedroom buyer, that is the value.
The conversion shaped the building. When the offering plan was filed, 32 apartments were reported as rent-stabilized, 21 as rent-controlled and four as vacant. The 32 and 21 already account for all 53 residences, so the four vacancies are either counted within those categories or come from a different schedule; check the plan's occupancy schedule before relying on the split. The plan was a non-eviction plan: tenants who did not buy stayed, and the sponsor held their apartments as unsold units. Amendments on file show the sponsor and other holders of unsold units carrying a declining block through the early 1990s. In June 1997 the sponsor conveyed its last twelve residences in two deeds, ten of them to a single successor holder.
The residue of that block is still intact. In 2011 the successor holder sold the five residences it had not yet sold off — 1E, 3B, 3C, 3D and 8D — to one investor entity in a single deed. That entity still holds all five: about 9.6 percent of the common interest and a similar share of common-charge revenue, per the audited statements, and the same five lots on the current roll. The block is small enough to leave governance with individual owners, but it is a remnant of the original sponsor inventory, and some or all of those apartments may still be occupied under the tenancies that existed at conversion.
Architecture and unit composition
The building fills a mid-block lot of about 8,860 square feet with a nine-story brick front over a cellar. The offering plan's engineer's report describes concrete-slab construction behind masonry walls and fireproof construction under the 1938 code classification, with two elevators — one passenger, one service — running from the basement.
Six apartments per floor across nine floors, less the ground-floor space given to the lobby, produce 53 residences. Five of the six lines are one-bedrooms; the B line is the building's two-bedroom, two-bath stack. With a median residence near 750 square feet on the assessment roll, this is a building for one-bedroom buyers, with a limited supply of two-bedrooms.
Because the building was fully regulated at conversion and apartments came to market one tenancy at a time over decades, interior condition varies widely. Some residences have been renovated; others were held under regulated tenancies until recently.
Building operations
Staffing. The offering plan budgeted a full-time superintendent and a full-time porter under the Local 32BJ agreement, with the superintendent living in the basement apartment. Payroll remains the largest line in the 2021 audited statements, and the forecast assumptions reference a security-services agreement alongside the union contract.
Capital posture. The condominium carries no underlying debt in the statements on file. It spent about $321,000 on major repairs in 2020 and $179,000 in 2021 — Local Law 11 façade inspection and repair work, hallway and stairwell upgrades, boiler tubes and elevator work — and levied a $50,000 special assessment over the first half of 2021 to rebuild reserves. The reserve fund stood at about $206,000 at December 31, 2021, down from about $567,000 two years earlier, and the board raised common charges 2 percent for 2022. The auditors note that no reserve study has been commissioned. Ask for the current reserve balance, the status of the current Local Law 11 cycle, and any assessment in force.
Taxes. The building received J-51 benefits for work begun in 1993, 1995 and 2001. The last abatement window ran from July 2001 through June 30, 2021, and no J-51 appears on the current roll. Taxes are at full assessment. The condominium retains counsel to protest the assessed value each year; tax-year protests were open from 2015/16 onward at the last statement date.
Policy framework
Ownership form. Condominium. Transfers run through the declaration and by-laws rather than a cooperative board approval; confirm whether the board holds a right of first refusal and how it is administered.
Sponsor. The original sponsor no longer holds units. The five-residence investor holding dates from 2011; whether it carries any holder-of-unsold-units rights under the plan should be confirmed with the managing agent.
Everything else. Pets, leasing terms, alteration rules and any transfer fee are not documented in the records located for this page. They should come from the managing agent and the current house rules.
Monthly carrying charges in recent sales
- Common charges + taxes, per room
- $532 per room a monthMedian of 3 recorded sales since October 2023Source: recorded sales, refreshed October 2026
- Common charges + taxes, per square foot
- $2.28 per square foot a monthMedian of 4 recorded sales since October 2023Source: recorded sales, refreshed October 2026
- Common charges alone, per square foot
- $1.17 per square foot a monthMedian of 3 listings since October 2023 that give the annual taxSource: listing records, refreshed October 2026
- Real estate taxes alone, per square foot
- $1.08 per square foot a monthMedian of 3 listings since October 2023 that give the annual taxSource: listing records, refreshed October 2026
Common charges plus real estate taxes, combined into one monthly figure the way New York condominium listings show them. Add a mortgage payment for the monthly outlay. The split into common charges and taxes comes from the listings that also give the annual tax, a different sample, so the two lines need not add up exactly to the combined median; a tax abatement can hold taxes below the full amount until it expires. A summary of recorded sales and listings, not a current bill; charges change.
Building staffing and amenities
- Doorman
- Part-time doormanSource: recent listing records
- Elevator
- YesSource: NYC Department of City Planning records (PLUTO)
Staffing and amenities as our building profile and recent listing records describe them. A feature not listed is not confirmed absent. Outdoor space, parking and some facilities can belong to particular apartments or to a separate owner; confirm access for the specific apartment.
Local Law 97
- 2024–2029 annual penalty
- $0 (under cap)
- 2030–2034 annual penalty
- $33,076/yr
- Per unit / month range
- $0 – $52
- Modeled exposure split equally across 53 units (the residential count on the city's lot record). Not an assessed amount; condominium owners are typically charged by each unit's common-interest percentage.
Source: NYC LL84 benchmarking and PLUTO · The Roebling Research Library. City data last refreshed October 2026.
See full Local Law 97 analysis — emissions history, scenarios, methodology →Facade safety — Local Law 11
The latest available filing classified the facade as SWARMP — Safe With A Repair and Maintenance Program: the inspector (QEWI) identified conditions requiring monitoring or repair, with repairs due by the deadline stated in the filing. The scope, timeline, and how the building funds the work are building-specific — we review the filings and board materials for you.
How to read this, and where it comes from
QEWI = Qualified Exterior Wall Inspector — a licensed professional engineer or registered architect who meets DOB’s FISP qualifications and signs the report (the independent expert, not the managing agent).
Source: NYC DOB facade filings (FISP) · The Roebling Research Library. City data last refreshed October 2026.
Photographs of The Westerly
Recent sales
The Westerly sells as a prewar condominium in a co-op neighborhood, and most of its trades are one-bedrooms. Compare dated sales with nearby prewar cooperative one-bedrooms and new-construction condominiums on Broadway and Columbus, adjusting for actual purchase requirements, apartment size, condition, amenities and carrying costs before assigning a price tier. Condition drives the spread inside the building more than floor, because the stock came out of regulated tenancy unevenly. The two-bedroom B line trades infrequently and sets the building's high end.
Recorded resales have run at a few per year for three decades; ACRIS shows five residential deeds in 2025, not all of them market sales. Comparables should be drawn from prewar condominium conversions on the Upper West Side, indexed to the last complete year.
Unit-level transaction history is maintained in The Roebling Research Library and shared with clients during diligence.
Recent closings at this building, from The Roebling Research Library. Prices are the transfer amounts recorded with the NYC Department of Finance; apartment-level detail is checked against the building’s own file in The Roebling Research Library before publishing.
| Date | Unit | Apartment | Price | PPSF | vs. Ask |
|---|---|---|---|---|---|
| Mar 4, 2026 | 5C | 2 BR · 1 BA · 1,100 sf | $1,100,000 | $1,000/sf | +0.0% |
| Dec 30, 2025 | 2D | 1 BR · 1 BA · 744 sf | $850,000 | $1,142/sf | +6.3% |
| Aug 6, 2025 | 9B | 3 BR · 2 BA · 1,325 sf | $1,875,000 | $1,415/sf | -1.1% |
| Jun 24, 2025 | 7D | 1 BR · 1 BA · 744 sf | $826,000 | $1,110/sf | — |
| Dec 23, 2020 | 4F | 1 BR · 720 sf | $695,000 | $965/sf | -1.4% |
| Jun 1, 2020 | 5F | 1 BR · 1 BA · 720 sf | $879,000 | $1,221/sf | +0.0% |
| May 16, 2019 | 9A | 1 BR · 1 BA · 720 sf | $745,000 | $1,035/sf | -0.7% |
| May 6, 2019 | 6C | 2 BR · 1 BA · 1,100 sf | $1,200,000 | $1,091/sf | -7.7% |
Market read. Most recent trades (2026 to date) cleared a median $1,060/sf (floor-adjusted) across 1 sale. Floor-adjusted means each sale is restated to a constant mix of floors, so the figure can differ from the plain median of the sales listed above. Median listing discount 0.6% from the last ask — a recurring negotiation gap worth pricing into any offer or listing strategy.
The retrade record
Lines that have traded more than once in the public record — the building’s appreciation arc, apartment by apartment.
Full closing history with price-per-square-foot over time, the complete retrade record, and every line that has traded.
Sales sourced from NYC Department of Finance recorded transfers (BBL 1-01223-7502; each condominium apartment is its own tax lot). Apartment-level facts (line, condition, asking-price context) curated and cross-verified in The Roebling Research Library. Not all transactions cross-verify with ACRIS records — sponsor and LLC purchases sometimes record at stipulated values rather than market price; square footage from recorded condo declarations and offering plans.
Closed rents at The Westerly, last 36 months
| Size | Leases | Median / month |
|---|---|---|
| 1 bedroom | 4 | $4,650 |
4 closed leases, October 2023 to September 2026. Most recent lease May 2026. Based on few leases. Sizes with fewer than 2 leases are not shown. Compiled by The Roebling Team at Compass from closed leases.
What would your apartment rent for?
The figures above are the building's closed leases. Enter your apartment and I'll send you what yours would rent for, from comparable leases at The Westerly and nearby.
At the recent median sale of $975K (4 sales in the past 24 months, since November 10, 2024), a buyer putting 25% down would pay about $35,180 to close, or 3.6% of the price.
- Mansion tax: $0
- Mortgage recording tax: $14,077
- Title insurance: $4,388
- Attorneys, lender, building fees, reserves and filings: $16,716
Assumes a resale (the seller pays transfer taxes), a $4,500 attorney fee and a mortgage on the rest.
Keep up with The Westerly and its market
The Roebling Report, monthly: Manhattan sales data and analysis, including buildings like The Westerly. Unsubscribe anytime.
We’ll use your email for The Roebling Report and note your interest in this building. See our privacy policy.
What to know if you’re buying
Price the condominium form. No co-op board interview; confirm financing and entity-ownership rules in the declaration, bylaws and house rules. Assess how those purchase requirements fit the buyer’s needs, and establish any tenure-related price difference from a dated, matched sales sample.
Underwrite from the current bill. The J-51 is gone, so there is no remaining phase-out; check the unit's current bill for any other benefit, and expect it to change with assessments, rates and any protest refunds.
Read the capital history. Façade cycles, hallway upgrades and a reserve that fell by more than half in two years are all in the 2020–2021 statements. Get the current figures before you sign.
Look behind the door. Decades of regulated tenancy mean a same-line apartment can be renovated or original. Price the renovation into the offer.
What to know if you’re selling
Lead with tenure. Prewar construction with condominium mechanics is the argument the surrounding co-ops cannot make. Put it at the top of the listing.
Answer the capital questions in advance. Reserve balance, Local Law 11 status and any assessment are the first things a buyer's attorney will ask for.
Position against the right competition. A renovated one-bedroom here competes with prewar condominium conversions and the lower end of Upper West Side new construction, not with co-op one-bedrooms that carry a board and a financing cap.
Comparable buildings
If you're considering The Westerly, also evaluate:
- 100 West 93rd Street — 100 West, the full-service condominium at the Columbus Avenue end of the same block; the amenity step-up
- 220 West 93rd Street — Jacob M. Felson's 1926 prewar condominium at Broadway; the same street and vintage
- 165 West 91st Street — The Mirabeau, a 1926 building converted to condominium in 2013; a later conversion of the same vintage
- 215 West 90th Street — Haroldon Court, a 1922 Rouse & Goldstone building converted to condominium in 2000
- 215 West 88th Street — The Merrion, a 1915 building converted to condominium in 2008
- 203 West 81st Street — The Barrington, a 55-residence prewar condominium conversion; the closest match on scale
- 150 West 82nd Street — The Marlow, George F. Pelham's 1926 building, converted under a non-eviction condominium plan with first closings in 2021–2022
- 127 West 82nd Street — The Greystone, another 1988 non-eviction condominium conversion of a regulated prewar building
More Upper West Side buildings
- 123 West 69th Street — 1882 condominium
- 123 West 74th Street — 1925 co-op
- 123 West 93rd Street — 1926 co-op
- 125 West 76th Street — 1922 co-op by George F. Pelham
- 127 West 79th Street (The Clifton House) — 1926 co-op
- 127 West 96th Street — 1930 co-op
The neighborhood
For the full corridor — architecture, transit, and pricing across Upper West Side — read The Roebling Team Guide to Upper West Side.
How to read the facts on this page. Items attributed to an offering plan describe the building as it was offered at that filing — unit mix, square footage, the amenity program as planned. They are not a statement about how the building operates today. Tax and compliance figures are sourced separately to current City records and carry their own dates. House rules, staffing and fee policy can change by board resolution without any public filing: treat every policy line here as a starting point for diligence and confirm it with the managing agent. Where this page compares one building or neighborhood to another, that is our analysis of the recorded record — it names the measure, the period and the sample it rests on, and it is an observation about medians rather than a prediction about any particular apartment.
Considering a move at The Westerly?
Request a private building brief with the relevant comparable sales, current and off-market availability, and an apartment-specific view of value.
646.939.7375 · c.cohen@compass.com