Can Your Neighbors Decide to Sell Your Home?
The Roebling Report · By Corey Cohen · Principal, The Roebling Team at Compass
At the Pierre and Miami's Biscayne 21, the value of an apartment became inseparable from the future of the building.
When you buy an apartment, you expect to share decisions about the roof, the elevators and the annual budget. You may give less thought to whether the other owners can decide it is time for everyone to sell.
The Pierre: the offer disappeared. The repair needs remained.
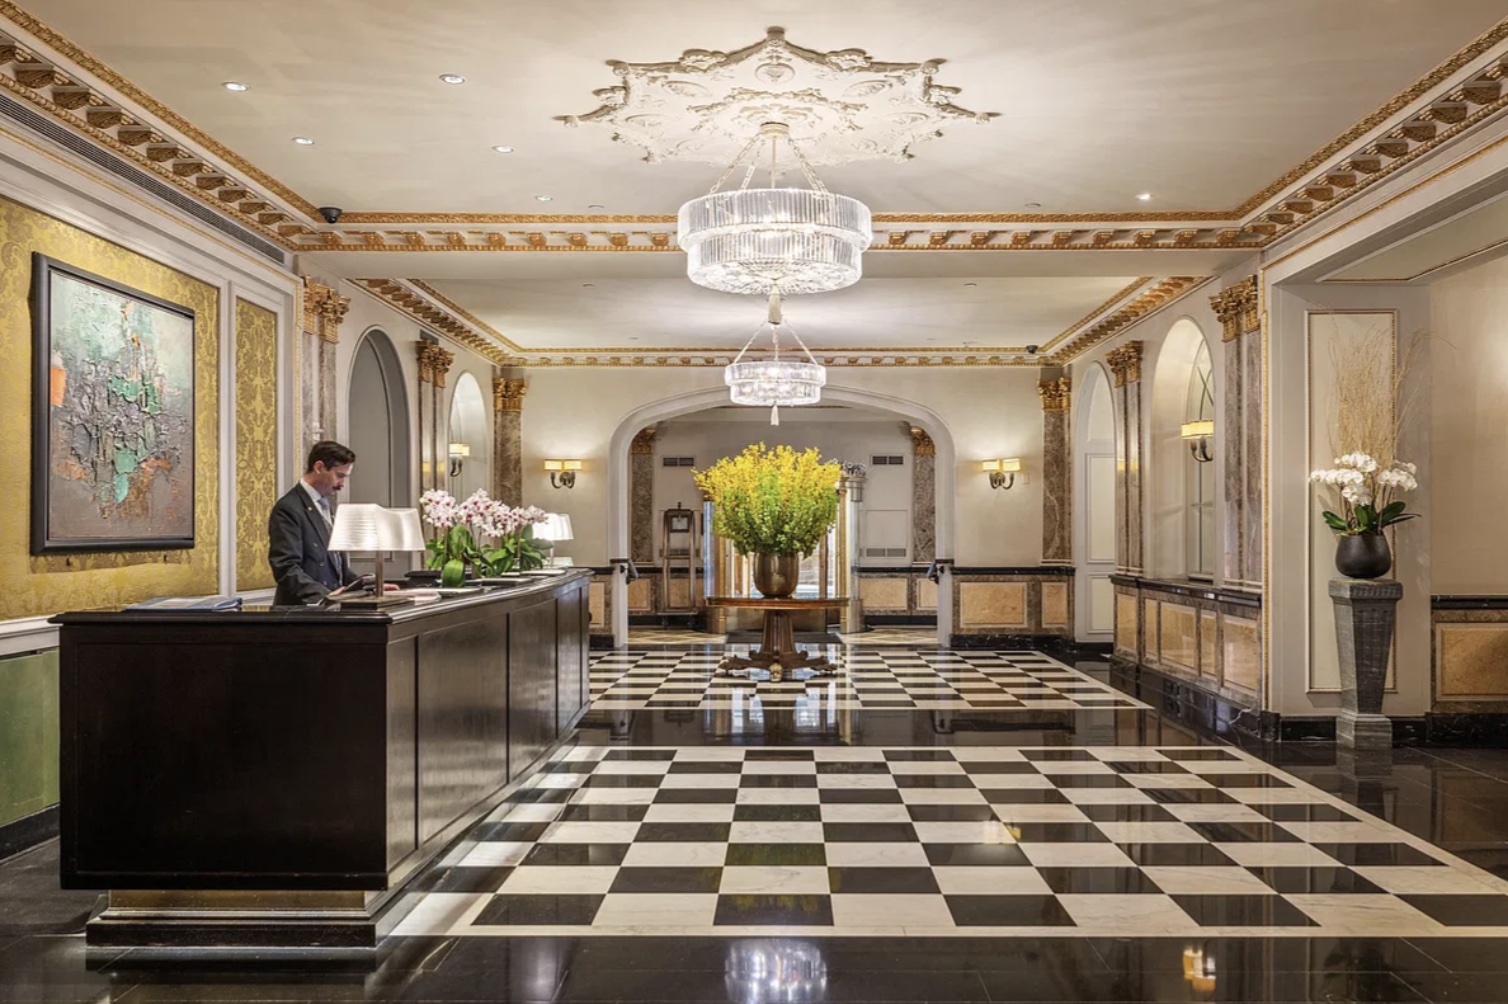
The Pierre opened in 1930 at 61st Street and Fifth Avenue. Behind its familiar hotel entrance is an unusual arrangement: a co-op corporation owns the building, which contains both hotel rooms and private apartments.
A proposed $2 billion sale to businessman Motasem Khashoggi covered both. The plan called for extensive renovation under the Dorchester Collection. Residents would sell and leave, with an opportunity to buy back into the renovated building later, potentially at a different price and in a different apartment.
According to published reporting, approval required holders of two-thirds of the co-op's shares. Owners who opposed the transaction could therefore have been required to leave. Actress Lois Chiles put the objection plainly: "Maybe I'm tired of moving, and I just want to live here."
There was a financial argument for selling, too. Engineers hired by the board were reported to have identified at least $182 million in repairs and upgrades. A sale could offer an exit from uncertain future bills.
The deal collapsed after the buyer missed an October 13, 2026, deadline for a $100 million deposit. A new engineering report has been commissioned, and the final repair costs and funding arrangements remain unsettled.
Owners avoided this transaction. They still need to pay for the building's work.
Biscayne 21: the owners won in court, then sold
In Miami's Edgewater neighborhood, Two Roads Development paid roughly $150 million for most of the units at Biscayne 21 in 2022. It planned to replace the 1964 waterfront condominium with a 55-story luxury tower.
Biscayne 21's declaration required unanimous consent to terminate the condominium, the legal process of ending its existing ownership structure. It also required unanimity for amendments affecting owners' voting rights. The developer-controlled association attempted to lower the termination threshold to 80%.
The remaining owners challenged the change. In a revised July 2025 opinion, Florida's Third District Court of Appeal held that removing their ability to withhold consent changed their protected voting rights. The association could not use that amendment to bypass unanimity.
The parties reached a settlement in late August 2026. Published reports, citing a developer representative, put the price for the remaining units at approximately $50 million. The site is now clear for that tower, branded EDITION Residences.
By then, the holdout residents had been displaced for nearly three years, and the building had been partly dismantled. Winning in court did not restore the community they had bought into.
The documents protected their negotiating position. Enforcing those protections still meant litigation and years away from home. Both belong in the calculation alongside the eventual payout.
Where I see the risks and opportunities
These cases involve different ownership structures: a New York co-op and a Florida condominium. Their approval requirements should not be assumed to apply to another building.
The broader South Florida backdrop adds another layer. Following Surfside, Florida imposed structural inspection and reserve-study requirements on covered condominium buildings. Associations facing reserve funding shortfalls may need additional assessments or borrowing.
For an owner facing substantial future bills, a buyout can be an attractive exit. It may also capture value that selling one apartment would not. But a premium to your apartment's resale value does not necessarily buy you an equivalent home elsewhere. Net proceeds, replacement costs and timing all matter.
For a buyer, an older building can offer value when the price reflects the required work and there is a credible plan to pay for it. I would be wary of paying for a rumored developer buyout that may never close.
Before calling an apartment a bargain, I would want four questions answered, with an attorney reviewing the governing documents:
- What work is needed, and what is funded? Look beyond today's monthly charges to engineering reports, reserves and planned assessments.
- Who controls the votes? An investor accumulating units may have different plans from the people living there.
- What can a majority approve? Review the sale, termination and amendment provisions, including which decisions require your consent.
- If there is an offer, can it close? Understand the buyer's financing, your expected net proceeds and when you would have to leave.
A building can be valuable enough to attract a buyer and expensive enough to put pressure on its owners at the same time. Understanding both is part of deciding what an apartment is worth.
Beyond Manhattan
Alongside my Manhattan practice, I'm now helping clients plan moves and second-home purchases in South Florida, Connecticut, Long Island, the Hamptons and New Jersey. I've built out market research, local guides and tools to compare transaction costs and ongoing ownership expenses.
I handle the New York City side and help coordinate the next purchase with local brokers. If you're considering a move, tell me the two markets you're weighing, and we can work through the numbers and timing together.
Approval thresholds, prices and dates for the Pierre and Biscayne 21 are as published in the reporting and court opinion cited above. Sale and termination rules differ by building and by state, and are set by each building's governing documents; nothing here describes any other building's rules. This is market commentary, not legal or tax advice. Have an attorney review the documents for any specific purchase or sale.