Murray Hill
Murray Hill runs east from Madison Avenue in the low 30s, a mix of surviving brownstone blocks and the large postwar buildings that replaced most of them. The stock is service-oriented, with full-time staff and conventional layouts rather than architectural distinction. Fewer sales clear above ask here than the Manhattan norm, so there is usually room to negotiate. Apartments are the smallest of any neighborhood we track and among the cheapest to carry, which is the trade buyers are making.
What the index shows for Murray Hill
Median condominium price per square foot and cooperative price per room, January–August 2026, with the change from the same months of last year, over the last full year, and since 2022 and 2016. Condos are measured by the foot, co-ops by the room. Rents are the median annual rent per square foot, with the same-apartment change.
January–August 2026 median: Murray Hill $1,228 · Midtown $1,510 · Manhattan $1,632
January–August 2026 median: Murray Hill $190K · Midtown $222K · Manhattan $271K
Medians of recorded, index-eligible sales. The headline price is January–August 2026, where at least 50 sales back it; otherwise the last complete year's. The charts show every complete year, and a year with too few sales is left as a gap rather than estimated; the hollow point is 2026 to date (the headline figure, where there is one), not a full year, and * means fewer than 30 sales behind it, so read it as directional. Like the annual medians it includes new-development first sales; the change from the same months of last year uses resales only, and appears only where at least 150 resales back each period. The longer changes run between complete years. The inflation-adjusted view deflates each year's median by the consumer price index to the last complete year's dollars (the current year uses an estimated index). Manhattan’s current-year figures are below 96th Street; its historical annual series also carries a small number of Upper Manhattan and unassigned sales. Each figure carries the mix of what happened to trade, not the like-for-like change of a single apartment. The count beside each change is the sample backing that comparison, which is smaller than the scope’s all-time total. Rents are medians of closed leases that report square footage, for condo and rental buildings; * means few leases. Compiled by The Roebling Team at Compass from public records. Figures are indicative, not an appraisal.
Latest closings in Murray Hill
The 10 most recent arms-length resales recorded across the buildings profiled here, newest first. Open a building for its full sales record.
| Closed | Building | Unit | Size | Price | $/sf |
|---|---|---|---|---|---|
| Sep 29, 2026 | Manhattan Place | 33K | 2 BR | $1,200,000 | $1,143 |
| Sep 29, 2026 | 302–310 Lexington Avenue | 3E | 1 BR | $525,000 | — |
| Sep 29, 2026 | 302–310 Lexington Avenue | 9F | Studio | $505,000 | — |
| Sep 28, 2026 | Lindley House | 9D | 1 BR | $355,000 | — |
| Sep 25, 2026 | 45 Park Avenue | 2101 | 2 BR | $2,575,000 | $1,695 |
| Sep 25, 2026 | The Hamilton | 10A | Studio | $410,000 | — |
| Sep 24, 2026 | Murray Hill House | 10C | 1 BR | $999,000 | — |
| Sep 24, 2026 | 80 Park Avenue | 18B | 1 BR | $947,500 | $1,151 |
| Sep 24, 2026 | The Carlton Regency | 8H | 1 BR | $555,000 | — |
| Sep 24, 2026 | The Vanderbilt | 9I | Studio | $515,000 | $1,272 |
Recorded deeds and transfer filings, compiled by The Roebling Team at Compass from public records. $/sf is shown for condominiums with a reported square footage. Sponsor first sales are not listed.
Murray Hill rents
Murray Hill rents are up 5.4% in January–September 2026, against the same months of 2025. 2025 was +4.9%, 2024 +2.8%, 2023 +0.4%.
The same apartments, lease to lease, each year against the year before (3,225 lease-to-lease comparisons). 2026 compares January–September with January–September 2025. The latest months can move as late-reported leases arrive.
| Size | 2023 | 2024 | 2025 | 2026 YTD |
|---|---|---|---|---|
| All sizes | $72361 leases−5.5% | $77538 leases+6.5% | $80488 leases+3.9% | $87462 leases+8.3% |
| Studio | $8558 leases | $8983 leases | $9475 leases | $10478 leases |
| 1 bedroom | $72183 leases−2.6% | $79297 leases+9.0% | $80269 leases+1.8% | $86260 leases+7.7% |
| 2 bedroom | $70105 leases−9.0% | $72137 leases+2.7% | $77118 leases+7.4% | $81109 leases+5.4% |
| 3 bedroom+ | $73*16 leases | $75*21 leases | $75*26 leases | $81*15 leases |
Median rent per square foot per year, from closed leases that report square footage. 2026 is January–September. * Fewer than 30 leases.
| Size | 2023 | 2024 | 2025 | 2026 YTD |
|---|---|---|---|---|
| All sizes | $1,217124 leases−2.7% | $1,250120 leases+2.7% | $1,400112 leases+12.0% | $1,446100 leases+3.3% |
| Studio | $1,25053 leases | $1,34958 leases | $1,44954 leases | $1,50061 leases |
| 1 bedroom | $1,13348 leases | $1,19845 leases | $1,33241 leases | $1,43330 leases |
| 2 bedroom | $1,247*22 leases | $1,245*15 leases | $1,344*16 leases | — |
Median monthly rent per room, co-op sublets. 2026 is January–September. * Fewer than 30 leases.
Compiled by The Roebling Team at Compass from closed leases, through September 2026. Figures are indicative, not an appraisal. The Roebling Index
How Murray Hill clears
What closings across Murray Hill look like at the table, shown against the Manhattan baseline so each figure reads as a comparison. Arms-length closings recorded from January 2024 onward, compiled October 4, 2026; each measure uses the closings with that field recorded.
- Typical closing vs asking price
- −3.6%
- Share selling above ask
- 8%
- Monthly charges
- $1,787
- Median rooms
- 3.0
At a glance
Where it is: The East Side from roughly East 34th to East 42nd Street, Madison Avenue to the East River, with Kips Bay below and Central Midtown above Share of recorded sales: cooperative 57 percent · condominium 37 percent · condop 4 percent · townhouse 1 percent Market character: 92.0 percent arm's-length across 14,275 recorded sales, sponsor-flagged activity at 4.4 percent — a deep resale record concentrated in a small number of very large buildings Defining control: the Murray Hill Historic District, designated January 29, 2002 and extended March 30, 2004 — a few blocks between Park and Lexington, leaving nearly every large building in the neighborhood outside landmark jurisdiction. Tudor City is designated separately, in 1988 Transit: 6 at 33rd Street; 4, 5, 6, 7 and S at Grand Central–42nd Street; Long Island Rail Road at Grand Central Madison since 2023. Nothing east of the Lexington Avenue line Watch for: the 2016 anchor. Both series stand lower in nominal terms in 2025 than in 2016, so a seller's last-cycle purchase price is not a floor here, and a comparable set that does not reach that far back will read the market backwards
Daily life and getting around
Murray Hill changes register about every two avenues, and the changes are abrupt. Between Park and Lexington in the mid-30s is the surviving piece of the original neighborhood — three- and four-story brownstone-faced row houses above raised basements, mostly Italianate. East of Third the scale changes completely: postwar towers of twenty and thirty stories, canopied entrances, garages, and side streets carrying far more traffic than the ones two blocks west. Between First and Second Avenues the ground opens into the Queens–Midtown Tunnel approach, a sunken road network running from 34th Street to 41st, with the eastbound entrance taken off 36th and the westbound exit surfacing at 37th. At the northeast corner the ground rises: Tudor City sits on a plateau above 42nd Street, reached by stairs and an overpass, with private parks and no through traffic.
Third and Second Avenues carry the day-to-day trade and the densest concentration of restaurants and bars here — an amenity on one block and a noise question on the next. Lexington runs quieter; Madison and the Park Avenue frontage are office and institutional rather than retail. Open space is thin, and St. Vartan Park at First and 35th is the main public option.
Transit is the sharpest value gradient here. The Lexington Avenue line stops at 33rd Street, and Grand Central–42nd Street at the northern edge puts the 4, 5, 6, 7 and S on one complex. Long Island Rail Road service began at Grand Central Madison on January 25, 2023 — a real change in the neighborhood's commuting position, and one that arrived after most of the pricing period the Index measures. East of Lexington there is no subway at all, and the walk to a train from First Avenue on a February morning is the most under-weighted variable in the tower tier. The neighborhood also sits inside the Congestion Relief Zone, tolled since January 5, 2025.
Why Murray Hill trades the way it does
Two facts sit under everything else. This is a resale record with almost nothing else in it — 92.0 percent arm's-length across 14,275 recorded sales back to 1996, sponsor-flagged activity at 4.4 percent. And both published series stand lower in nominal terms in 2025 than in 2016: the cooperative per-room median by 5.5 percent, the condominium per-square-foot median by 4.0 percent, each giving back close to 29 percent once inflation is taken out. Nine years, no nominal gain, on either tenure.
Read together, those numbers close off the usual explanations. At 4.4 percent sponsor-flagged there is no absorption cycle in the record to blame, no wave of first-sales to filter out before a comparable means anything. Households sold to households across the whole period, and in 2025 they sold for less than households sold for in 2016. The local evidence does not support carrying a 2016 basis forward as a floor.
A third fact explains why the record moves as one thing. Those 14,275 sales are spread across only 273 addresses, and the five most-traded account for roughly 22 percent of the entire history between them — 330 East 38th Street at 853 recorded sales, 5 Tudor City Place at 667, 300 East 40th Street at 589, 320 East 42nd Street at 540 and 25 Tudor City Place at 523. A market that concentrated offers deep comparable evidence and very little scarcity to defend a price with. At these addresses a buyer's agent can assemble a same-line comparable set in an afternoon, and no seller has an argument available that the apartment is hard to replace.
The stock
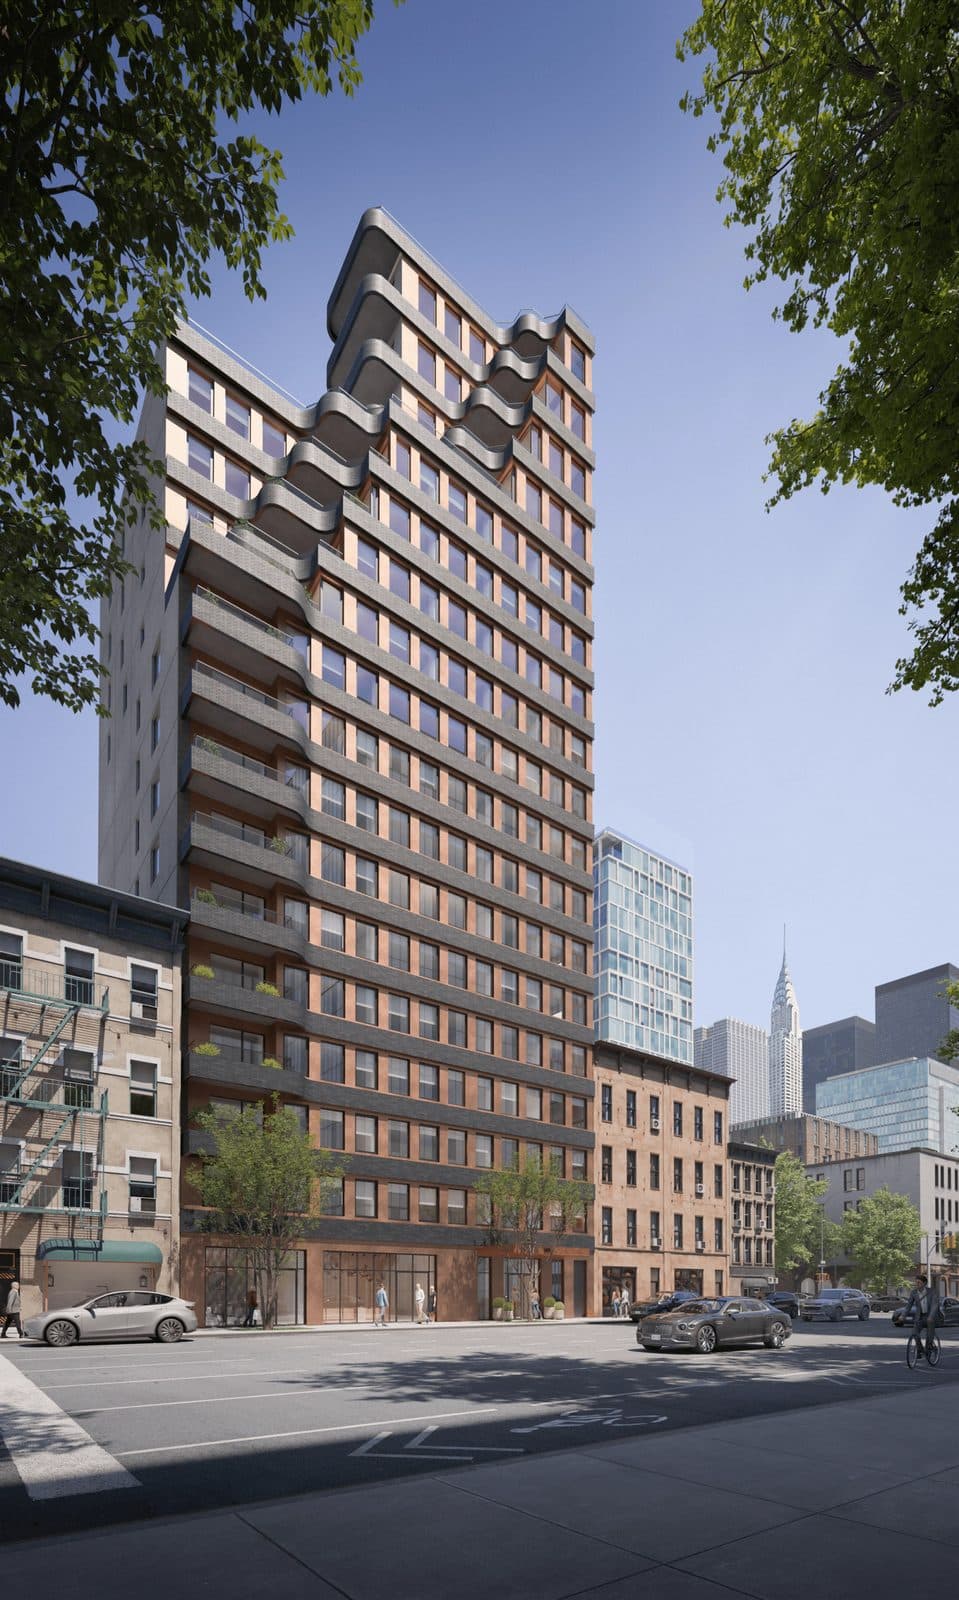
The postwar and late-twentieth-century service buildings are the volume — large elevator buildings with full-time staff, running east from Third Avenue and north toward 42nd. 330 East 38th Street, the 57-story Corinthian, is the outer bound of the type and the most-traded address in the neighborhood: 863 apartments completed in 1988 to a Der Scutt design, built on the former East Side Airlines Terminal site with the tower placed to clear a Queens–Midtown Tunnel tube running beneath the block. 300 East 40th Street, 333 East 34th Street and 630 First Avenue are the working middle of the same tier, and where most of the 37 percent condominium share sits.
The prewar cooperatives and converted row houses between Madison and Third are the older and much smaller half — 55 Park Avenue among them. They turn over rarely and their board terms are the most restrictive in the neighborhood. Three nearby addresses often grouped with them are condominiums and sell on condominium terms, not cooperative admission: 45 Park Avenue, new construction completed in 2006; 80 Park Avenue, a 1950s rental building converted to condominium; and 211 Madison Avenue, Morgan Court, completed in 1985. Tudor City is the third product, treated on its own below.
Price the cooperative stock per room with the board terms attached and the condominium stock per square foot. That matters more here than in most neighborhoods, because apartments in Murray Hill run small: a headline price that reads as a bargain against the rest of the East Side frequently will not read that way per square foot. Floor area in the co-op tier is usually an estimate rather than a survey, so treat any per-square-foot figure taken from a co-op listing as approximate, and check room counts against the floor plan.
The covenant, and the district that arrived late
Murray Hill was governed privately long before it was governed publicly, and both regimes are narrower than their reputations. When the Murray heirs settled a final partition agreement in 1847, they wrote restrictive covenants into the deeds of the divided farmland: brick or stone dwellings only, residential use, no commerce, and an explicit bar on museums, theaters, circuses and the exhibition of wild animals. The Murray Hill Restriction held those blocks to row-house use for most of seventy years, then failed — by the 1920s the Morgan family had exhausted its efforts to enforce the covenants, and conversion to apartments and offices moved quickly afterward. That failure is why the brownstone fabric survives in fragments rather than as a continuous district.
Public protection came eighty years later and covers very little. The Landmarks Preservation Commission designated the Murray Hill Historic District on January 29, 2002 — row houses of the 1850s through the 1920s, Italianate and Second Empire, plus three apartment buildings, an architectural office and a church, on a few blocks between Park and Lexington. Two extensions followed on March 30, 2004, taking in 114 to 134 East 36th Street and 124 to 130 East 37th Street and joining the two segments of the original district. Sniffen Court, the alley of ten brick stables of 1863 and 1864 off East 36th Street, was designated separately on June 21, 1966 and is among the smallest districts in the city.
Inside those boundaries, most exterior work needs Landmarks approval — a staff-level permit or a Certificate of Appropriateness, depending on the work — and the schedule and cost that come with it belong in your read of a building's capital plan. Outside them — where the overwhelming majority of the neighborhood's apartments are — none of it applies unless the building is individually designated. The National Register listing, made in 2003 and expanded in 2013 to some 250 buildings, is larger than the city district and confers no alteration control at all; the two are routinely conflated, and only one constrains an owner.
Tudor City
Tudor City is a separate market inside the neighborhood boundary and behaves like one. Fred F. French built it on the bluff above 42nd Street from the mid-1920s under H. Douglas Ives's design direction, the first buildings opening on September 30, 1927 with roughly 2,800 apartments; the last was finished in 1956. The complex turned its back on the river deliberately — First Avenue then carried slaughterhouses, meat-packing plants and gasworks, so the towers were built with very few east-facing windows, which is why so many apartments look inward at the private parks rather than out at the river. Those parks were nearly lost: after Harry Helmsley bought the complex in 1970 and proposed replacing them with towers, residents fought the plan and the parks were preserved by a 1972 rezoning. The Landmarks Preservation Commission designated the Tudor City Historic District on May 17, 1988, following the National Register listing in September 1986.
Eleven of the thirteen buildings are cooperatives, with one rental and one hotel among them, so most of what trades here is shares and board approval rather than a deed. 5 Tudor City Place and 25 Tudor City Place are the second and fifth most-traded addresses in the neighborhood, so comparable evidence at those two is exceptionally deep; 1 Tudor City Place and 2 Tudor City Place sit under the same designation.
What to know if you're buying here
Build the comparable set back to 2016, not back three years. Both series are down in nominal terms across that span, and a seller working from a last-cycle purchase price will produce a very different number than the recorded history supports.
Use the depth — it is the best thing this market gives you. At 92.0 percent arm's-length, with hundreds of recorded trades at the largest addresses, the sale history at your target building is real market evidence rather than a sponsor's pricing schedule. Pull the address's own record, and the line, before any neighborhood-level figure.
Underwrite the board before the apartment. With cooperatives at 57 percent of the sale record and condops at a further 4 percent, the binding constraint is approval, not price. Get the financing cap, post-closing liquidity requirement, sublet policy and flip tax from the managing agent in writing before you make an offer. The condop share is small but it is the tenure most often mislabelled, and a condop is not underwritten like a condominium.
Establish which side of the landmark line the building sits on. Inside the 2002 district or its 2004 extensions, façade and window work needs Landmarks approval (a staff-level permit or a Certificate of Appropriateness, depending on the work); outside, the same work is a permit and a contractor. The National Register listing is not evidence of either.
Price the block, not the neighborhood. The tunnel approach between First and Second Avenues, the Second and Third Avenue bar corridor and the walk to Lexington vary street by street and floor by floor. See the specific line at night and on a weekday morning before paying a premium for an exposure.
What to know if you're selling here
You have no scarcity argument, so lead with condition and line. Where five addresses carry roughly a fifth of all recorded sales, a buyer can price you against a dozen near-identical apartments. What moves the number is renovation quality, exposure, floor and line — set the price from those and be precise, because the buyer has the same record you do.
Board terms are part of the price. A low financing ceiling or a restrictive sublet policy narrows the buyer pool before anyone sees the apartment. Price for the pool you actually have, and plan a longer marketing period rather than discovering the constraint through three months of failed applications.
Bring the carrying cost forward on day one. Assessments, façade cycles, the underlying mortgage and, in the condominium tier, the tax position on the specific unit are what re-trade deals here. A seller who can answer those with documents in hand removes the most common cause of a renegotiation — and in a market that has not appreciated in nominal terms since 2016, a re-trade is expensive.
Where it sits in the Index
Murray Hill publishes without a caveat — 11,160 index-eligible sales across 65 building profiles, running back to 1996 — and both its series stand on their own rather than leaning on the parent market. It is the East Side's clearest case of a deep, liquid, non-speculative record that still lost ground in real terms between 2016 and 2025, which makes it a useful control against the sponsor-heavy readings elsewhere on the map. See the Roebling Index for the current read.
Run the numbers
Related guides
- Kips Bay — A Buyer's Guide — the neighborhood directly south, and the closest comparable postwar market
- Central Midtown — A Buyer's Guide — across 42nd Street, and a different buyer entirely
- Manhattan Apartment Buying Guide
- NYC Real Estate Tax & Closing Cost Guide
Buildings in Murray Hill

Get the neighborhood read on your building.
See how your apartment compares with the rest of Murray Hill, or get a market update tuned to this neighborhood — sent to you directly.
646.939.7375 · c.cohen@compass.com
The same research for the markets NYC owners most often weigh against an apartment: town guides, closing costs and the monthly cost of owning a house.
- Moving between NYC and the suburbs →
- Long Island →
- Westchester →
- Connecticut →
- New Jersey →
- South Florida →
Carrying-cost calculators (mortgage, property tax by town, insurance, upkeep): Long Island · Westchester · Connecticut · New Jersey · Boca Raton & Delray Beach